Shopping cart
Your cart empty!

Your cart empty!

Join 10k+ people to get notified about new posts, news and tips.
Do not worry we don't spam!
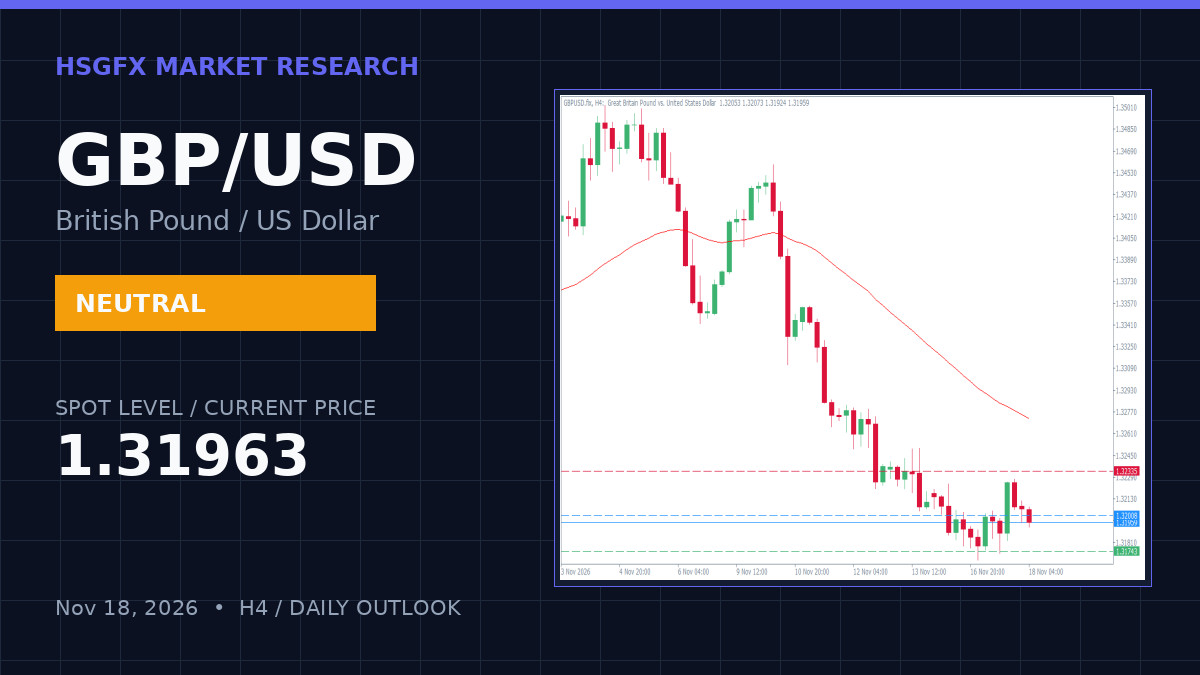
London, HSGFX - Foreign exchange markets shifted their focus toward sterling crosses on Wednesday as traders recalibrated monetary policy expectations for the United Kingdom. The currency pair faced immediate downward pressure during the New York session following updated macroeconomic trajectories that outline persistent price pressures ahead.
At the core of the recent shift in market sentiment is the newly projected trajectory for British consumer prices. Fresh economic modeling indicates that United Kingdom inflation is on course to peak at 4.5% in the first quarter of 2027. This anticipated resurgence in headline inflation has forced interest rate derivatives traders to re-evaluate the anticipated timeline of upcoming Bank of England monetary easing cycles.
The recalibration of United Kingdom yield curves directly influences cross-border capital flows into London. Fixed-income desks note that longer-dated gilt yields have responded swiftly to the medium-term inflation outlook, narrowing the yield differentials between British gilts and comparable sovereign debt instruments across international jurisdictions.
Foreign exchange strategists across major financial institutions in London and New York point out that monetary policy divergence remains the primary driver for major currency pairs. As the Bank of England navigates the challenge of anchoring medium-term price stability while supporting domestic economic activity, currency participants are closely monitoring incoming employment and wage growth prints.
Meanwhile, the broader United States Dollar Index continues to hold a dominant position across global trading floors. Greenback strength stems from ongoing evaluations of the Federal Reserve policy path, keeping risk sentiment subdued across European and Asian session desks.
Commodity and currency desks in Frankfurt and Tokyo observe that cross-asset volatility remains elevated as macro traders balance the implications of sticky global inflation against shifting central bank reaction functions. The interplay between US Treasury yields and European sovereign debt continues to dictate short-term technical ranges for spot foreign exchange.
Looking ahead, global market participants are preparing for a dense calendar of incoming macroeconomic releases. Upcoming consumer price index reports, labor market statistics, and preliminary purchasing managers index surveys from major economies will provide vital clues regarding global economic momentum.
Central bank communication from Washington, D.C., and London will likewise remain under intense scrutiny by institutional algorithmic traders and macro hedge funds. As the first quarter of 2027 approaches, data dependency will continue to dictate positioning across sterling and dollar-denominated assets.